Study Abroad Education Loan for Indian Students: Collateral, Documents, Visa Funds and Repayment Guide
An overseas university offer can feel like the finish line. Financial planning often proves it is only the beginning. Tuition is paid in another currency, living costs continue every month, visa authorities may require evidence of available funds, and the education loan can affect the family years after graduation. A rushed loan decision may secure admission but create avoidable interest, documentation or disbursement problems.
Indian students searching for an education loan for study abroad need to compare more than interest rates. Eligibility, margin money, collateral, co-applicant strength, recognised-course policies, foreign-exchange movement, sanction conditions, moratorium and repayment flexibility all influence the real cost. This guide provides a structured way to prepare, compare and coordinate the loan with the university and visa timeline.
Quick answer: Start six to nine months before intake. Build the complete course budget, compare secured and unsecured loan options, strengthen the student and co-applicant file, obtain a clear sanction letter, map every visa and university deadline, understand currency and tax-related charges, and read the repayment terms before accepting.
1. Calculate the total study-abroad cost
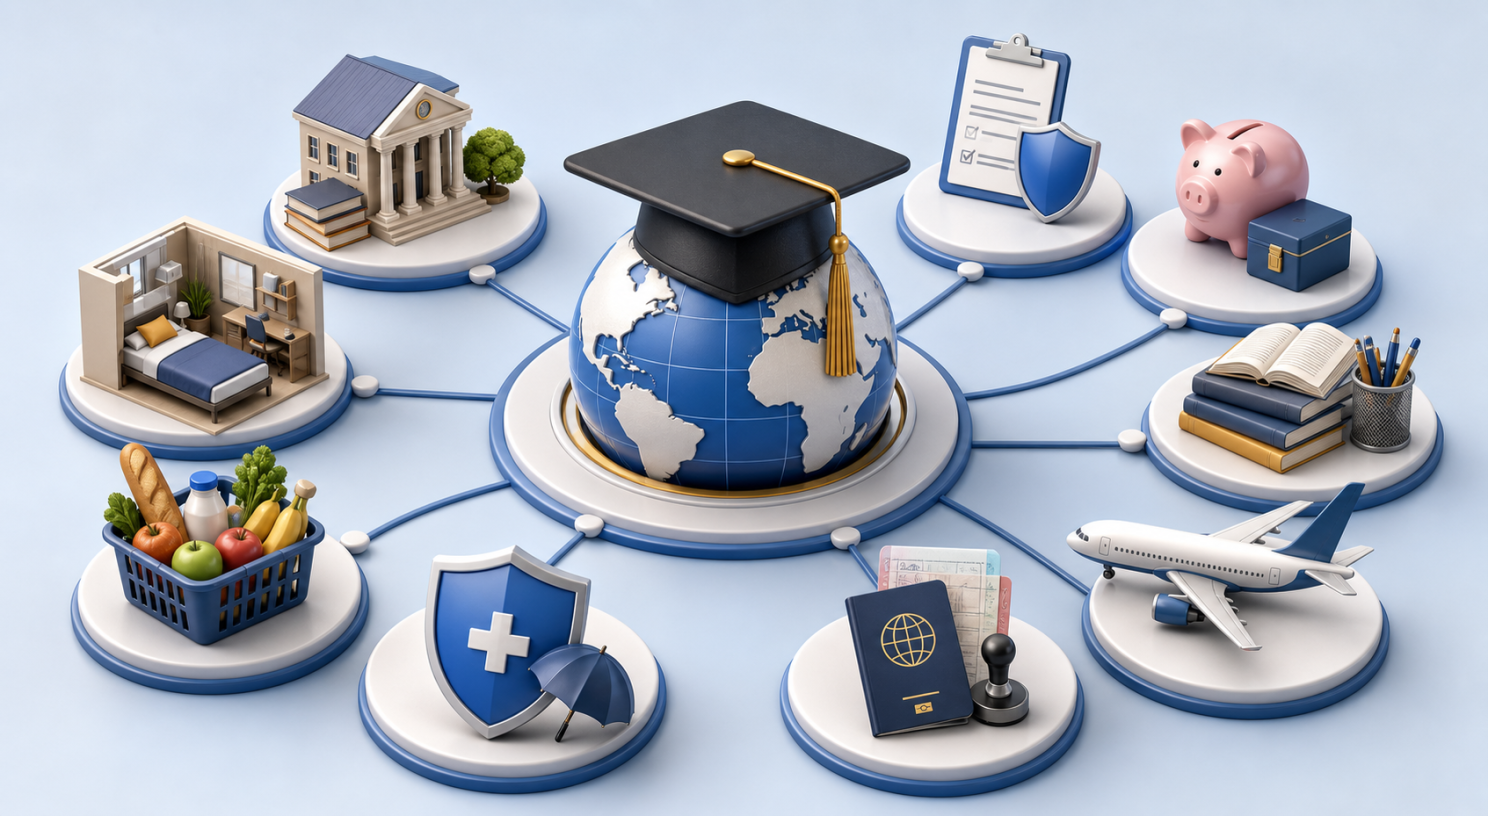
Do not apply only for the first-year tuition shown on the offer letter. Prepare a course-level budget covering tuition, university fees, deposit, accommodation, food, health insurance, visa and immigration charges, flights, local transport, books, equipment and a reasonable emergency buffer. Consider course duration and likely annual fee changes.
Separate costs by currency and payment date. A sanction amount that appears sufficient in rupees may become tight if the exchange rate moves before later disbursements. Ask the university which charges are mandatory, refundable or estimated.
2. Understand secured and unsecured education loans
Secured loans
A secured education loan uses acceptable collateral under the lender’s policy. This may support a larger amount or different pricing, but the property or asset documents require careful examination. Valuation, legal opinion, ownership, existing charge and insurance can extend the timeline. The family should understand the consequence of default before offering security.
Unsecured loans
An unsecured loan is assessed through the student’s academic and employability profile, institution and course, co-applicant income, credit history and lender policy. Faster processing or no property collateral does not automatically mean the lowest total cost. Compare interest, fees, insurance, moratorium treatment and repayment conditions.
No lender or consultant can responsibly guarantee approval. Policies can differ by institution, destination, programme and intake.
3. Check student eligibility before applying
Lenders commonly review admission status, academic consistency, test scores where relevant, course level, university recognition, destination, age and career prospects. Backlogs, study gaps or a change of field need a clear explanation supported by documents. A strong offer from a recognised institution helps, but it is not the only factor.
Keep passports, marksheets, degree certificates, entrance or English-test results, offer letters, fee schedules and scholarship letters consistent. Differences in name spelling, address or dates should be corrected or explained early.
4. Prepare the co-applicant profile
The co-applicant may be a parent, spouse or other eligible person under lender policy. Banks and financial institutions assess identity, relationship, income stability, existing obligations, credit history and repayment capacity. Organise salary slips or business financials, bank statements, tax returns and proof of current loans.
Do not hide an obligation or submit altered records. Credit checks and bank analysis can reveal inconsistencies and damage confidence. If income is seasonal or comes from a business, prepare a simple explanation of cash flow with supporting documents.
5. Build the document file in advance
• Student and co-applicant identity, address and relationship documents
• Passport and admission or conditional offer letter
• Academic records, test scores, CV and work-experience proof
• Detailed university fee structure and estimated living costs
• Scholarship, assistantship or personal-funds evidence
• Income, employment, business and bank documents
• Existing loan statements and credit-related explanations
• Collateral title, tax, approval and valuation material where applicable
Use a document index and consistent filenames. A complete, readable file can reduce repeated requests during a time-sensitive application.
6. Compare the real cost of borrowing
Interest rate is important, but it is not the whole comparison. Ask whether the rate is fixed or floating, which benchmark and spread apply, how often it resets, and whether interest accrues during study and moratorium. Understand processing, legal, valuation, insurance, remittance and late-payment charges.
Request an illustration showing disbursement dates, accrued interest and expected EMI under reasonable assumptions. Compare the annual percentage and total repayment where the lender provides it. Small differences become significant over a long tenure.
7. Read the moratorium correctly
A moratorium usually delays full EMI; it does not necessarily stop interest from accruing. Confirm the period during study, the additional grace period and whether simple or compounded treatment applies under the product terms. Ask whether paying interest during study reduces the later burden or earns any concession.
Plan for the possibility that employment takes longer than expected. The loan contract remains binding even when the graduate is searching for work. Families should maintain a contingency reserve rather than assuming the first salary will arrive immediately after graduation.
8. Coordinate loan sanction with visa funds
Countries and institutions have different requirements for proof of funds, acceptable financial institutions, holding periods, tuition payment and document wording. A general loan approval may not satisfy the exact visa evidence requirement. Match the sanction letter, disbursement ability and fund availability to the official immigration checklist for the intended route.
Use current government and university sources because rules can change between intakes. Confirm whether living expenses, dependant funds, deposits or prepayments must be shown separately. Avoid unexplained last-minute transfers.
9. Understand sanction, conditions and disbursement
A sanction letter can contain conditions that must be fulfilled before money is released. Read validity, security creation, margin contribution, original-document requirements, insurance, guarantor terms and destination restrictions. Confirm whether disbursement goes directly to the university, reimburses paid expenses or supports living costs through a defined mechanism.
Map each tuition deadline and allow processing time. Currency conversion, intermediary banking and international transfer cut-offs can affect receipt. Keep invoices, remittance confirmations and university acknowledgements.
10. Plan margin money and family contribution
Some loans require the family to contribute a percentage of eligible costs. Clarify which expenses count and when the contribution must be paid. Savings should also cover non-eligible items, deposits and emergencies.
Do not exhaust every liquid rupee for margin money. The family still needs an emergency reserve, and the student may face initial expenses before local banking or part-time income is available.
11. Evaluate scholarships and part-time work conservatively
A confirmed scholarship reduces borrowing. An application for a scholarship does not. Include only documented awards in the committed funding plan. Part-time work rules and job availability vary; treat potential earnings as support rather than the foundation of tuition repayment.
Students should understand work-hour restrictions, academic expectations and taxation in the destination. Violating visa conditions can create consequences far greater than the short-term income.
12. Prepare for repayment before departure
Estimate EMI at different interest rates and exchange-rate scenarios. Decide whether repayment will come from overseas income, Indian family income or both. Understand prepayment, part-payment, foreclosure, mandate and overseas-remittance options. Maintain contact details with the lender while abroad.
Create a simple annual review: outstanding principal, interest rate, credit record, income, emergency fund and prepayment capacity. Refinancing may sometimes help, but fees, collateral release and new conditions require comparison.
Common education-loan mistakes
• Applying after the visa deadline is already close
• Comparing only the advertised interest rate
• Ignoring living costs and foreign-exchange movement
• Submitting incomplete or inconsistent documents
• Assuming moratorium means interest-free study
• Offering collateral without understanding legal consequences
• Depending entirely on uncertain scholarships or part-time work
• Accepting a sanction without reading disbursement conditions
How Tamil Nadu students can organise the process locally
Students in Chennai, Coimbatore, Madurai, Trichy and other Tamil Nadu cities can reduce delay by preparing one verified master file before visiting lenders. Scan originals clearly, keep physical copies in the same order and create a timeline covering offer acceptance, deposit, loan application, property legal review where required, visa filing and tuition transfer. When a co-applicant lives in another district, confirm early whether signatures, bank visits or original documents must be completed at a specific branch.
Ask every lender to put important terms and pending conditions in writing. Record the officer, branch, date and next action after each discussion. If the university changes the fee or start date, send the revised document promptly. Local guidance can help coordinate the moving parts, but the student and family should read the lender’s final sanction and the destination government’s official financial-evidence instructions themselves.
Frequently asked questions
Can I get a study-abroad loan without collateral?
Possibly, depending on the student, institution, course, co-applicant and lender policy. Approval amount, pricing and conditions vary.
When should I apply?
Begin research before receiving the final offer and make a complete application as soon as the required admission documents are available. Secured files may need additional legal and valuation time.
Does the education loan cover living expenses?
Many products include eligible living expenses within defined limits, but the sanction and disbursement method must be checked. Visa evidence rules are separate.
Can a consultant guarantee a visa after loan sanction?
No. A loan is one part of the financial evidence. Immigration authorities decide visas under current rules and the complete application.
Finance the degree with the same care used to choose it
An education loan should connect the student’s academic plan, family capacity, visa timeline and future repayment. When these pieces are reviewed together, the family can make a decision based on total value instead of urgency.
AKS Overseas Education supports Indian students with course and university selection, applications, documentation, financial-readiness planning, visa coordination and pre-departure guidance. Students should obtain loan terms directly from authorised lenders and verify current visa rules through official government sources.
Disclaimer: This article is general educational information, not a loan recommendation, financial advice or visa guarantee. Lending and immigration requirements change. Verify current terms with the lender, university and relevant government authority.